A Bank Reconciliation Statement (BRS) is a statement prepared to explain the differences between the balance shown by the Cash Book and the balance shown by the Pass Book. These differences usually arise because of timing differences, bank transactions, or errors. In this guide, you will learn the meaning, format, adjustment rules, overdraft treatment, and solved BRS problems with simple explanations.
BRS stands for Bank Reconciliation Statement.
Bank Reconciliation statement is prepared to reconcile the difference between the Cash Book balance and Pass Book balance.
BRS Adjustment Rules: When to Add and Deduct :
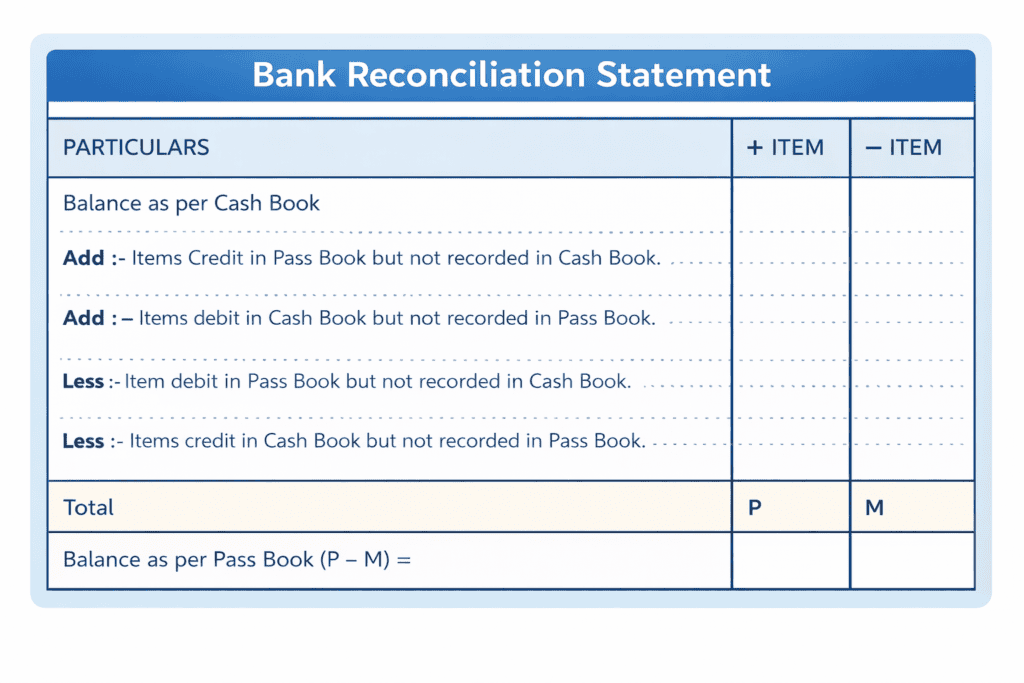
What is Bank Reconciliation Statement?
When you maintain a Cash Book in your accounts, your bank also maintains a Pass Book (Bank Statement) for you. Both books record the same transactions — but sometimes their balances do not match.
The statement prepared to explain the difference between Cash Book balance and Pass Book balance is called the Bank Reconciliation Statement (BRS).
| Simple Definition: BRS = A statement that bridges the gap between Cash Book balance and Pass Book balance. |
Why Do the Two Balances Differ?
There are 3 main categories of reasons:
Category 1 — Time Gap Reasons (Most Common)
| Situation | Who Records First? | Why Difference? |
| Cheque issued but recipient has not gone to bank yet | Only Cash Book (Cr.) | Bank does not know yet |
| Cheque deposited but bank has not cleared it yet | Only Cash Book (Dr.) | Bank processing pending |
Category 2 — Bank Acts Without Telling You
| Situation | Who Records First? |
| Bank deducts charges | Only Pass Book |
| Bank credits interest | Only Pass Book |
| Bank collects cheque/bill on your behalf | Only Pass Book |
| Bank pays insurance/loan EMI directly | Only Pass Book |
| Customer deposits directly into your account | Only Pass Book |
| Cheque deposited dishonoured (bounced) | Only Pass Book |
Category 3 — Errors (Tricky — Exam Favourite!)
| Type of Error | Where it Happens |
| Wrong amount recorded | Cash Book or Pass Book |
| Entry recorded twice | Cash Book or Pass Book |
| Entry completely missed | Cash Book or Pass Book |
| Casting mistake (addition error) | Cash Book |
| Cheque recorded in CB but never sent to bank | Cash Book |
The Master Rule — Learn This Once, Use Forever
When you START with Cash Book Balance (Favourable/Debit Balance):
| Item | Do This |
| Cheque issued but NOT presented to bank | ➕ ADD |
| Cheque deposited but NOT cleared by bank | ➖ DEDUCT |
| Bank charges NOT in Cash Book | ➖ DEDUCT |
| Interest/Dividend credited by bank NOT in Cash Book | ➕ ADD |
| Direct deposit by customer NOT in Cash Book | ➕ ADD |
| Direct payment by bank (insurance, EMI) NOT in Cash Book | ➖ DEDUCT |
| Cheque deposited dishonoured (bounced) NOT in Cash Book | ➖ DEDUCT |
| Cheque issued returned (technical reason) NOT in Cash Book | ➕ ADD |
| Receipts side of Cash Book undercast | ➕ ADD |
| Payments side of Cash Book undercast | ➖ DEDUCT |
| Receipts side of Cash Book overcast | ➖ DEDUCT |
| Payments side of Cash Book overcast | ➕ ADD |
| Note: Result after applying all items = Pass Book Balance. If starting from Pass Book, FLIP every ADD and DEDUCT. |
Overdraft — The Most Confusing Part (Explained Simply)
Normally your Cash Book shows a Debit Balance (money you have). When you spend more than you have, the bank gives you a temporary loan — now your Cash Book shows a Credit Balance. This is called Bank Overdraft (OD).
| Situation | Normal Balance | Overdraft (OD) |
| Cheque issued not presented | ➕ ADD | ➖ DEDUCT |
| Cheque deposited not cleared | ➖ DEDUCT | ➕ ADD |
| Bank charges not in CB | ➖ DEDUCT | ➕ ADD |
| Interest by bank not in CB | ➕ ADD | ➖ DEDUCT |
Level 1 — Basic BRS
| QUESTION The Cash Book of Arun shows Dr. balance of ₹15,000 on 31st March 2024. On comparing with Pass Book, the following differences were found: (i) Cheques issued but not yet presented to bank – ₹4,000 (ii) Cheques deposited but not cleared – ₹3,000 (iii) Bank charges not entered in Cash Book – ₹250 (iv) Interest credited by bank not in Cash Book – ₹750. Prepare BRS and find Pass Book balance. |
Bank Reconciliation Statement of Arun
As on 31st March 2024
| Particulars | ₹ | ₹ |
| Balance as per Cash Book (Dr.) | 15,000 | |
| ADD: | ||
| Cheques issued but not presented to bank | 4,000 | |
| Interest credited by bank (not in Cash Book) | 750 | 4,750 |
| 19,750 | ||
| LESS: | ||
| Cheques deposited but not cleared by bank | 3,000 | |
| Bank charges not in Cash Book | 250 | 3,250 |
| Balance as per Pass Book (Cr.) | 16,500 | |
Level 2 — Find Cash Book Balance (Working Backwards)
| QUESTION Pass Book of Meena shows Cr. balance of ₹20,000 on 31st March 2024. (i) Cheques issued but not presented – ₹5,000 (ii) Cheques deposited but not cleared – ₹3,500 (iii) Bank paid LIC premium directly – ₹1,500 (iv) Dividend collected by bank – ₹2,000 (v) Bank charges – ₹300. Find Cash Book balance. |
| Working — Finding CB Balance CB Balance = PB Balance – Items to ADD + Items to DEDUCT = 20,000 – (5,000 + 2,000) + (3,500 + 1,500 + 300) = 20,000 – 7,000 + 5,300 = Rs. 18,300 |
Bank Reconciliation Statement of Meena
As on 31st March 2024
| Particulars | ₹ | ₹ |
| Balance as per Cash Book (Dr.) [Calculated] | 18,300 | |
| ADD: | ||
| Cheques issued but not presented | 5,000 | |
| Dividend collected by bank (not in CB) | 2,000 | 7,000 |
| 25,300 | ||
| LESS: | ||
| Cheques deposited but not cleared | 3,500 | |
| LIC premium paid by bank (not in CB) | 1,500 | |
| Bank charges (not in CB) | 300 | 5,300 |
| Balance as per Pass Book (Cr.) ✓ | 20,000 | |
Level 3 — Casting Errors (Undercast / Overcast)
| Understanding Casting Errors: Receipts side undercast → CB balance is LESS → ADD the short amount Receipts side overcast → CB balance is MORE → DEDUCT the excess Payments side undercast → CB balance is MORE → DEDUCT the short amount Payments side overcast → CB balance is LESS → ADD the excess |
| QUESTION Cash Book shows Dr. balance of ₹12,000 on 30th June 2024. (i) Cheques deposited ₹8,000 only ₹6,500 credited by bank (ii) Receipts column of Cash Book undercast by ₹200 (iii) Customer deposited ₹3,000 directly in bank only in Pass Book (iv) Cheques issued ₹9,200 only ₹2,200 presented for payment in July (v) Bank credited interest ₹330; bank charges ₹60. Prepare BRS. |
| Key Workings Cheques issued not presented = Rs.9,200 – Rs.2,200 = Rs.7,000 Cheques deposited not cleared = Rs.8,000 – Rs.6,500 = Rs.1,500 Receipts undercast -> CB balance is less -> ADD Rs.200 |
Bank Reconciliation Statement
As on 30th June 2024
| Particulars | ₹ | ₹ |
| Balance as per Cash Book (Dr.) | 12,000 | |
| ADD: | ||
| Cheques issued but not presented (9,200 – 2,200) | 7,000 | |
| CB receipts undercast (add short amount) | 200 | |
| Customer direct deposit not in CB | 3,000 | |
| Interest credited by bank | 330 | 10,530 |
| 22,530 | ||
| LESS: | ||
| Cheques deposited but not cleared (8,000 – 6,500) | 1,500 | |
| Bank charges | 60 | 1,560 |
| Balance as per Pass Book (Cr.) | 20,970 | |
Level 4 — Wrong Amount Recorded
| Golden Rule for Wrong Amount Errors: Adjustment = Correct amount – Wrong amount recorded (adjust only the DIFFERENCE, not full amount!) |
| QUESTION Cash Book (Dr. balance) ₹25,000 on 31st March 2024. (i) Cheques issued not presented — ₹6,000 (ii) Cheques deposited not cleared — ₹4,500 (iii) Bank charges not in CB — ₹300 (iv) Bank paid insurance ₹2,000 — recorded in CB as ₹200 (v) Interest by bank ₹800 — not in CB (vi) Cheque received ₹2,000 deposited — dishonoured, not in CB |
| Key Working — Item (iv) Wrong Amount Insurance actually paid = Rs.2,000 Recorded in Cash Book = Rs.200 CB shows Rs.1,800 MORE than it should -> DEDUCT Rs.1,800 (the difference only, NOT the full amount!) |
Bank Reconciliation Statement
As on 31st March 2024
| Particulars | ₹ | ₹ |
| Balance as per Cash Book (Dr.) | 25,000 | |
| ADD: | ||
| Cheques issued but not presented | 6,000 | |
| Interest credited by bank (not in CB) | 800 | 6,800 |
| 31,800 | ||
| LESS: | ||
| Cheques deposited but not cleared | 4,500 | |
| Bank charges (not in CB) | 300 | |
| Insurance short recorded (2,000 – 200) | 1,800 | |
| Dishonoured cheque (not in CB) | 2,000 | 8,600 |
| Balance as per Pass Book (Cr.) | 23,200 | |
Level 5 — Bills of Exchange in BRS
| Term | Meaning |
| Bill Discounted | You gave a bill to bank; bank gave money immediately at a small discount |
| Bill Retired | Bill paid before due date — bank gives you a rebate (discount for early payment) |
| Bill Dishonoured | Bill not paid on due date — bank reverses the payment and may charge extra |
| Bill for Collection | You gave bill to bank to collect on due date — bank credits when collected |
| QUESTION Cash Book shows Dr. balance of ₹10,000 on 31st December 2024. (i) Cheque to Karan ₹500 not presented (ii) Bill ₹700 retired rebate ₹20 full ₹700 credited in Cash Book (iii) Cheque ₹295 deposited dishonoured (iv) ₹800 deposited credited in Pass Book as ₹80 (bank error) (v) Payments side CB undercast by ₹200 (vi) Bill receivable ₹1,000 discounted Nov dishonoured 31st Dec – not in CB |
| Key Workings Item (ii): Bill retired. Rebate=20. CB shows 700 but bank credited 680. DEDUCT Rs.20 (rebate only) Item (iv): Bank error – credited 80 instead of 800. Bank credited 720 less. ADD Rs.720 Item (v): Payments undercast -> CB balance is MORE -> DEDUCT Rs.200 |
Bank Reconciliation Statement
As on 31st December 2024
| Particulars | ₹ | ₹ |
| Balance as per Cash Book (Dr.) | 10,000 | |
| ADD: | ||
| Cheque to Karan — not presented | 500 | |
| Bank error — short credit (800 – 80) | 720 | 1,220 |
| 11,220 | ||
| LESS: | ||
| Rebate on bill not recorded in CB (700 – 680) | 20 | |
| Cheque deposited — dishonoured | 295 | |
| Payments side CB undercast | 200 | |
| Bill discounted — dishonoured — not in CB | 1,000 | 1,515 |
| Balance as per Pass Book (Cr.) | 9,705 | |
Level 6 — Overdraft (OD) Question
| QUESTION Cash Book shows Cr. balance (Overdraft) of ₹8,000 on 31st March 2024. (i) Cheques issued not presented — ₹2,000 (ii) Cheques deposited not cleared — ₹2,500 (iii) Interest on overdraft charged — ₹60 — not in CB (iv) Bank charges — ₹100 — not in CB (v) Pass Book shows credit ₹1,000 — ₹400 by debtor directly + ₹600 interest on investment — not in CB (vi) Cheque ₹200 recorded in CB but never sent to bank |
| Overdraft Rule — Everything FLIPS! Normal: Cheque issued not presented -> ADD | In OD: -> DEDUCT Normal: Cheque deposited not cleared -> DEDUCT | In OD: -> ADD Normal: Bank charges -> DEDUCT | In OD: -> ADD (increases what you owe) |
Bank Reconciliation Statement
As on 31st March 2024
| Particulars | ₹ | ₹ |
| Overdraft as per Cash Book (Cr.) | 8,000 | |
| ADD: (Items that increase overdraft) | ||
| Cheques deposited but not cleared | 2,500 | |
| Interest on OD not in CB | 60 | |
| Bank charges not in CB | 100 | 2,660 |
| 10,660 | ||
| LESS: (Items that decrease overdraft) | ||
| Cheques issued but not presented | 2,000 | |
| Direct deposit by debtor + interest on investment | 1,000 | |
| Cheque recorded in CB but never sent to bank | 200 | 3,200 |
| Overdraft as per Pass Book (Dr.) | 7,460 | |
Level 7 — Partial Cheques
| Key Rule: Only the UNPRESENTED portion causes the BRS difference. Cheques presented BEFORE the date = already in both books = NO difference. Ignore them. |
| QUESTION Cash Book (Dr. balance) ₹12,000 on 31st March 2024. (i) Total cheques issued ₹10,000 — ₹3,000 presented in March, ₹4,000 presented in April, rest not presented. (ii) Total cheques deposited ₹5,000 — ₹1,500 credited in March, rest credited in April. (iii) Bank charges ₹100; interest credited ₹200 (iv) CB receipts side undercast ₹500 |
| Key Workings — Partial Cheques Cheques issued not yet presented = Rs.4,000 (April) + Rs.3,000 (never) = Rs.7,000 (Rs.3,000 presented in March = already in both books = no difference) Cheques deposited not cleared = Rs.5,000 – Rs.1,500 = Rs.3,500 |
Bank Reconciliation Statement
As on 31st March 2024
| Particulars | ₹ | ₹ |
| Balance as per Cash Book (Dr.) | 12,000 | |
| ADD: | ||
| Cheques issued not presented (4,000 + 3,000) | 7,000 | |
| Interest credited by bank (not in CB) | 200 | |
| CB receipts side undercast | 500 | 7,700 |
| 19,700 | ||
| LESS: | ||
| Cheques deposited not cleared (5,000 – 1,500) | 3,500 | |
| Bank charges (not in CB) | 100 | 3,600 |
| Balance as per Pass Book (Cr.) | 16,100 | |
Level 8 — Board Exam Comprehensive (13 Adjustments)
| QUESTION Starting from Pass Book Cr. balance ₹12,400 on 31st March 2024. (a) Cheques issued not presented ₹500. (b) Cheque issued returned on tech. grounds ₹4,000 — not in CB (c) Cheque deposited not in CB ₹500 (d) Commission charged ₹27; Interest allowed ₹330 (e) Amount wrongly debited by bank ₹2,400 (f) Short credit for cash deposit ₹90 (g) CB credit side undercast ₹200 (h) Insurance premium not in CB ₹600 (i) Bill for collection credited by bank ₹8,000 (j) Bank charges entered TWICE in CB ₹20 (k) Cheque received entered TWICE in CB ₹1,000 (l) Bill discounted dishonoured not in CB ₹5,000 (m) Rebate on payment of bill by bank not in CB ₹200 |
Bank Reconciliation Statement
As on 31st March 2024 | Starting from Pass Book Balance
| Particulars | ₹ | ₹ |
| Balance as per Pass Book (Cr.) | 12,400 | |
| PLUS ITEMS (to reach Cash Book): | ||
| (c) Cheque deposited not recorded in CB | 500 | |
| (g) CB credit side undercast | 200 | |
| (j) Bank charges entered twice in CB | 20 | |
| (i) Bill for collection credited by bank | 8,000 | |
| (m) Rebate on payment of bill not in CB | 200 | |
| MINUS ITEMS (to reach Cash Book): | ||
| (a) Cheques issued not presented | 500 | |
| (b) Cheque issued returned — not in CB | 4,000 | |
| (d) Interest allowed by bank — not in CB | 330 | |
| (d) Commission charged by bank | 27 | |
| (e) Amount wrongly debited by bank (bank error) | 2,400 | |
| (f) Short credit for cash deposit (bank error) | 90 | |
| (h) Insurance premium not recorded in CB | 600 | |
| (k) Cheque received entered twice in CB | 1,000 | |
| (l) Bill discounted dishonoured — not in CB | 5,000 | |
| Balance as per Cash Book (Dr.) = 12,400 + 8,920 – 13,947 | 7,373 | |
Master Cheat Sheet — Every Item at a Glance
| Item | Start from CB (Dr.) | Start from PB (Cr.) |
| Cheque issued not presented | ➕ ADD | ➖ DEDUCT |
| Cheque deposited not cleared | ➖ DEDUCT | ➕ ADD |
| Bank charges not in CB | ➖ DEDUCT | ➕ ADD |
| Interest credited by bank not in CB | ➕ ADD | ➖ DEDUCT |
| Direct deposit by customer not in CB | ➕ ADD | ➖ DEDUCT |
| Direct payment by bank not in CB | ➖ DEDUCT | ➕ ADD |
| Cheque dishonoured not in CB | ➖ DEDUCT | ➕ ADD |
| Cheque issued returned not in CB | ➕ ADD | ➖ DEDUCT |
| CB receipts undercast | ➕ ADD | ➖ DEDUCT |
| CB payments undercast | ➖ DEDUCT | ➕ ADD |
| CB receipts overcast | ➖ DEDUCT | ➕ ADD |
| CB payments overcast | ➕ ADD | ➖ DEDUCT |
| Bill discounted dishonoured not in CB | ➖ DEDUCT | ➕ ADD |
| Rebate on bill — full amount in CB | ➖ rebate only | ➕ rebate only |
| Bank error — excess debit | ➕ ADD | ➖ DEDUCT |
| Bank error — short credit | ➕ ADD | ➖ DEDUCT |
5-Minute Exam Revision — Memory Tricks
| 1. Issued not presented → ADD (from CB) 2. Deposited not cleared → DEDUCT (from CB) 3. Bank does something without telling me → find the direction 4. Overdraft → flip every rule 5. Partial cheques → only unpresented portion counts 6. Wrong amount → adjust only the difference, not full amount 7. Casting error → think: does it make CB more or less? |

Swathika B is an MBA graduate in Finance & Business Analytics , the founder of The Commerce Lab. With a strong academic foundation in B.Com BFSI and hands-on experience in financial analysis, data analytics, and business studies, she created this platform to make Commerce and Accountancy simple, practical, and exam-ready for students across India.